Bank reconciliation process flowchart
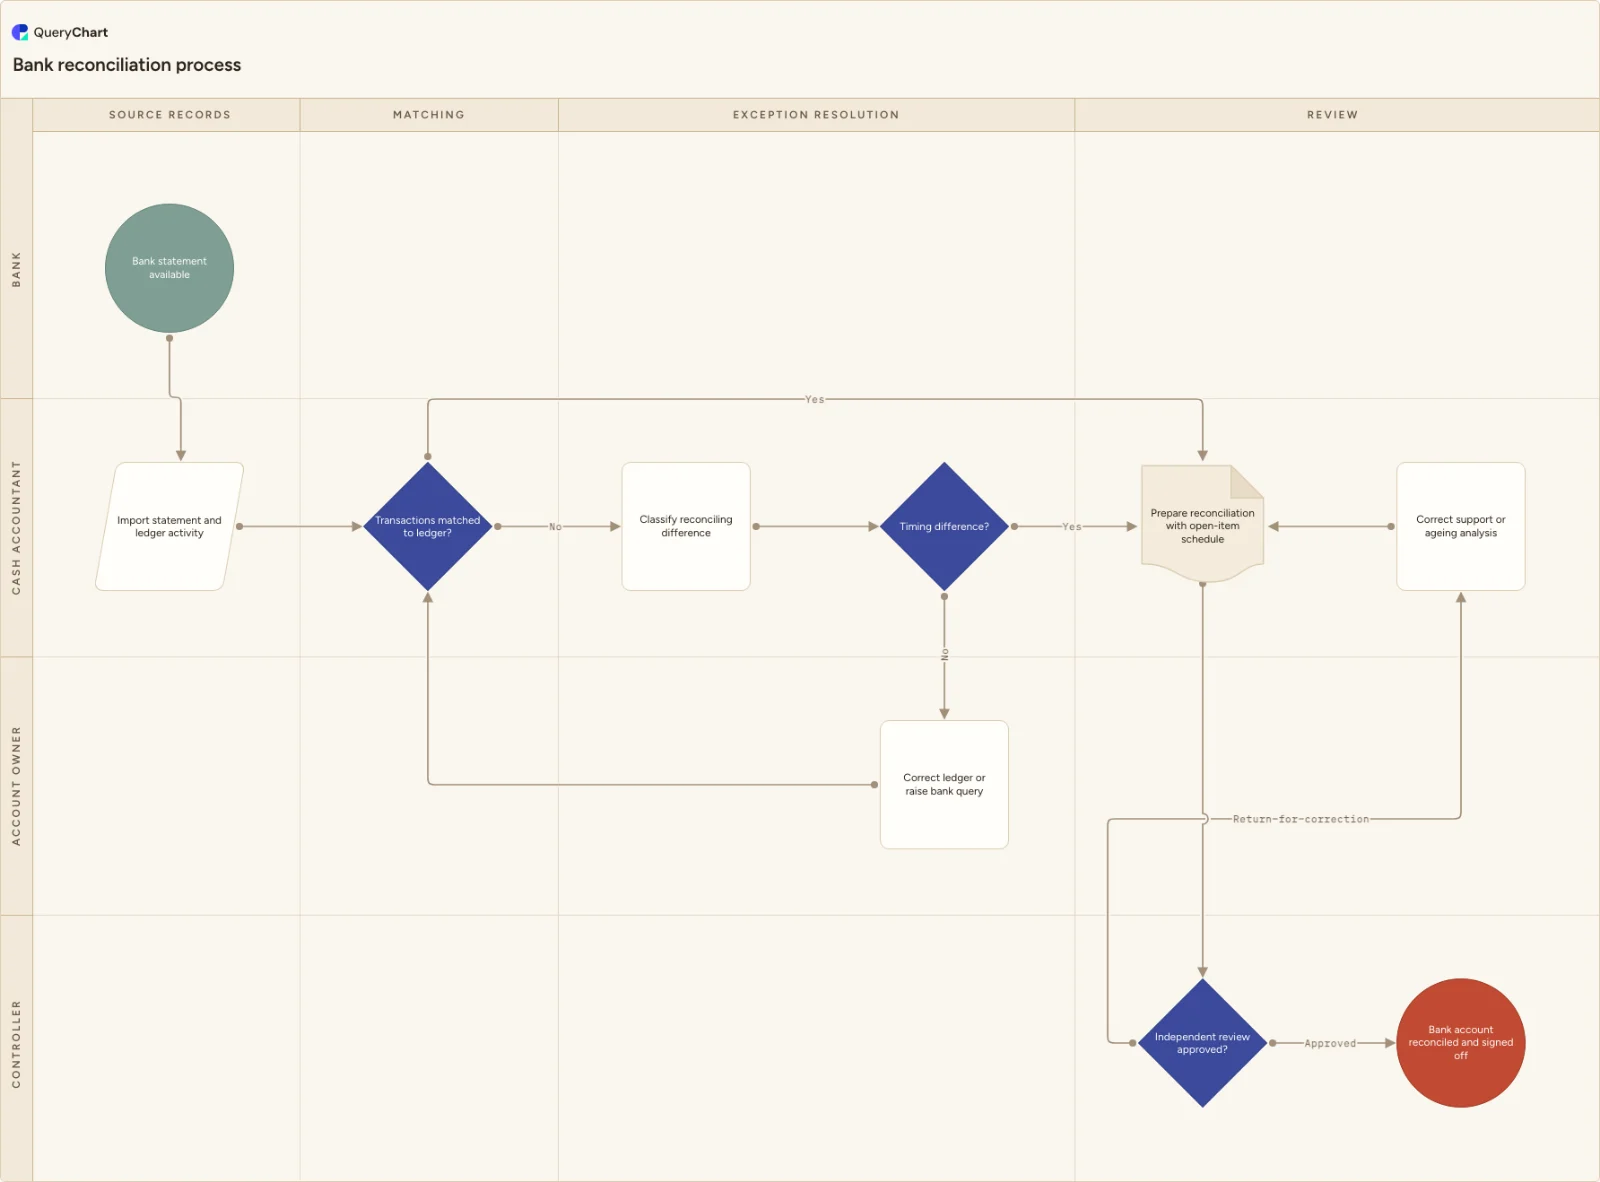
Bank reconciliation process flowchart for matching bank statements to the general ledger, resolving timing and error differences, and independent sign-off.
What the bank reconciliation process is
A bank reconciliation is not simply a report that happens to balance. It explains every difference between the bank statement and the cash ledger as a timed, evidenced item, a ledger correction or a bank query. That distinction is what makes the reconciliation useful at close and defensible in a control review.
The chart separates the preparer, account owner and controller. The cash accountant builds the match and ageing schedule, the account owner helps resolve operational exceptions, and the controller independently reviews the evidence and rejects incomplete work. A reviewer should never be asked to approve their own preparation.
What this flowchart covers
In this template
- Importing the bank statement and cash-ledger activity into one matching population.
- A split between genuine timing differences and ledger or bank errors, with evidence and an owner for every open item.
- An independent reviewer sign-off loop that returns weak support or stale open items for correction.
When to use this template
- You are documenting a daily, weekly or month-end bank reconciliation control.
- Open bank items are being carried forward with no explanation, ageing or clear owner.
- You need to separate reconciliation preparation from review for audit or financial-close purposes.
How it works
Agree source timing
Set when statements, bank feeds and ledger extracts are considered complete for the reconciliation period.
Define open-item evidence
Require a date, source reference, reason, owner and expected clearance date for each timing difference.
Keep review independent
Assign the reviewer outside the preparer role and state which aged or unusual items must be escalated.
Frequently asked questions
What is a bank reconciliation?
A bank reconciliation compares transactions and balances on a bank statement with the organisation's cash ledger, explains every difference, and documents review of the completed schedule.
What is a timing difference?
A timing difference is a legitimate transaction recorded by one source but not yet the other, such as a payment in transit. It needs evidence and an expected clearance date, not an unexplained carry-forward.
Who should approve a bank reconciliation?
A reviewer independent of the preparer should review the reconciliation, supporting evidence and aged open items. The exact role depends on the organisation's segregation-of-duties design.
Where this process fits
In most operations this process follows Payment approval process flowchart.
It is one step in Order-to-cash.
Step 1: Customer credit approval process flowchart (limit and terms)
Step 3: Proof of delivery process flowchart (ePOD capture to invoice)
Step 5: Accounts receivable process flowchart (invoice to cash)
A five-lane accounts receivable process flowchart: credit check, invoice issue, payment terms, dunning, disputes, payment plans, cash application, write-off.
Step 6: Bank reconciliation process flowchart You are here
Bank reconciliation process flowchart for matching bank statements to the general ledger, resolving timing and error differences, and independent sign-off.